Since 2014 · GAF and Owens Corning Certified
How a Roof Insurance Claim Actually Works
Have us look before you file. Then you file the claim, the adjuster comes out and writes an estimate, and we check that the work can be done for that amount. Ruddy's Roofing in Round Rock walks you through it.
 Have us look
before you file. You file the claim
with your carrier. We check the
adjuster's estimate. You pay your
deductible, by law.

Your Deductible
You pay your own deductible. Texas law requires the deductible to be paid on replacement cost benefit insurance claims, and Texas law prohibits contractors from covering or waiving your deductible.
A roofer who offers to cover it is billing your insurance company for work that is not being done.
Deductibles are per storm date. If you replace your roof now and hail hits again next month, the deductible applies again.
Some insurance companies require proof you paid the deductible, such as a canceled check, before they release the depreciation.
The Claim, Step by Step
Six steps, in the order they happen.
- 1Have Us Look First.
We inspect the roof for storm damage from wind or hail.
 2You File the Claim.
You file a claim with your insurance carrier.
 3The Adjuster Comes Out.
The adjuster schedules an inspection of your roof.
- 4The Estimate.
If the adjuster finds damage from a storm, they write an estimate.
- 5We Check the Estimate.
We make sure it is written correctly and the work can be done for that amount.
 6Finish in Time.
You have six months or one year to get the work done, or you lose the second payment.
Insurance Words, in Plain English
The words on your paperwork, one line each.
- Adjuster
- The person your insurance company sends to look at the damage and write the estimate.
- Deductible
- Your out of pocket expense, usually 1% to 2% of your home's value.
- Depreciation
- Money held back from the first check. There are two kinds, recoverable and non recoverable.
- Recoverable Depreciation
- The second check is coming. With these policies, all you pay is the deductible.
- Non Recoverable Depreciation
- No second check is coming. These policies are rare, and you owe the deductible and the depreciation held out.
- RCV
- Replacement Cost Value. An RCV policy has recoverable depreciation.
- ACV
- Actual Cash Value. An ACV policy has non recoverable depreciation.
Insurance Claim Questions We Get Asked
What Is Recoverable Depreciation?
It is the second check. The insurance company holds back depreciation from the first check. If you get the work done for the total of the estimate, they pay the recoverable depreciation after the work is done, and your only out of pocket expense is the deductible. Most policies work this way.
What Is the Difference Between RCV and ACV?
An RCV policy, Replacement Cost Value, has recoverable depreciation, so a second check comes after the work is done. An ACV policy, Actual Cash Value, has non recoverable depreciation. No second check is coming, and you owe the deductible and the depreciation held out. ACV policies are the rare ones.
Should I Call You Before or After I File?
Before. Have us inspect the roof for storm damage first, then file the claim with your carrier. After the adjuster writes the estimate, let us review it so we know it is written correctly and the work can be done for that amount. In the meantime, do not sign anything a door knocker hands you.
Our Roofing Services

Roof Replacement
Most jobs are done in one day, and we need no money to start.
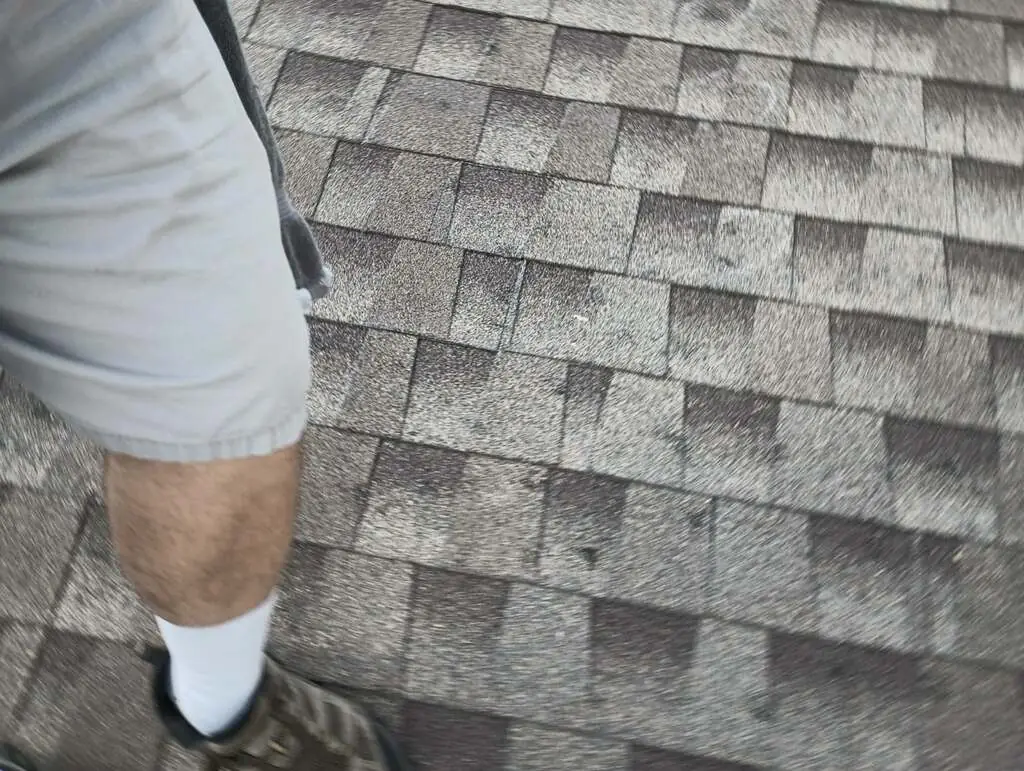

Free Roof Inspection
No charge to come out. If the roof is fine, that is what we tell you.

Roof Repair
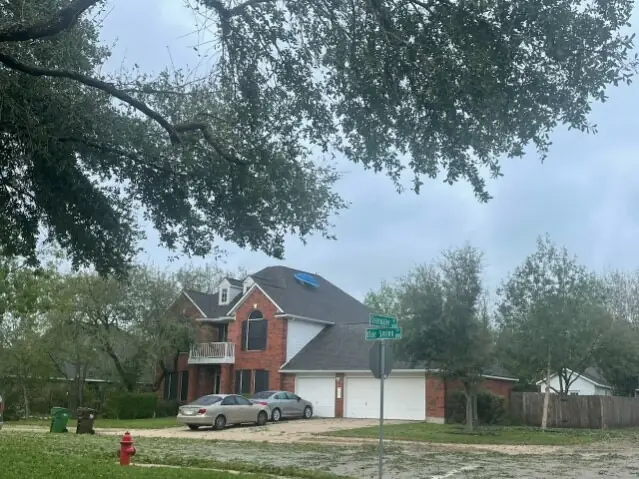
We repair shingle roofs: ridge caps, blown off shingles and leaks after a rain.

After a Hail Storm
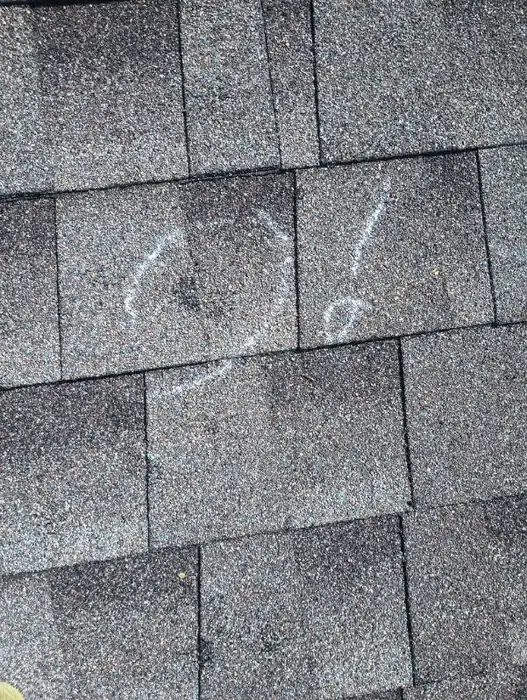
You cannot see hail damage from the ground. We walk the roof and chalk it.
Where We Work
Travis and the surrounding counties.


Start With a Free Look at Your Roof
No charge to come out, no money to start, and if the roof is fine, that is what we tell you.